Download the ABCD app

Unlock Financial Tools, Investment Insights, And Expert Guidance – All In One Convenient App !

Visit Our ABCD Page

What Is Housing Finance?

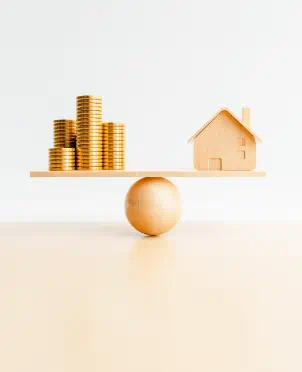
Housing Finance helps you achieve your dream of being a homeowner. It offers convenient financing solutions to buy, build, and renovate a house. It also lets you get hassle-free loans against your owned property, unlocking its true potential.

  • banner_image
    Attractive interest rates
  • banner_image
    Quick & transparent processing
  • banner_image
    Customised solutions

Our Housing Finance Plans

Compare Our Housing Finance Plans

A quick glance at how housing finance plans differ from each other.

PLAN TYPE HOME LOAN TOP-UP HOME LOAN BALANCE TRANSFER LOAN AGAINST PROPERTY
Purpose To finance buying a new housing property To receive extra payout upon existing home loan for extra costs To transfer home loan to another lender for better benefits To take a home loan with already-owned property as collateral
Best For Anyone looking to buy their dream home Home loan borrowers falling short on funds Home loan borrowers who find extended tenure or better interest rates with another lender Anyone with existing property looking to buy a new one
Tenure Up to 30 years Not more than existing home loan tenure Up to 30 years Up to 20 years
Processing Fee Generally 1% of loan amount + taxes Generally 0.5% to 2% of the loan amount 0.50% t0 2.50% of the loan amount
Interest Rates 7.75% p.a.* Depending on various factors 8.00% to 17.50% p.a.* 8.95% to 18.50% p.a.*
APPLY NOW APPLY NOW APPLY NOW APPLY NOW

ABC OfCalculators

HOME LOAN AMOUNT
Tenure (1 to 30 Years)
Rate of Interest (7 to 25%)
I CAN PAY EMI OF
Tenure (1 to 30 Years)
Rate of Interest (7 to 25%)

Your estimated EMI amount

₹ 0

Total Interest

₹ 0

Total Payout

₹ 0
CURRENT AGE
MONTHLY INCOME
YOUR CURRENT MONTHLY OBLIGATIONS

You are eligible for a loan of

₹ 0*
For a tenure of0 years

EMI @ 9% Interest Rate

₹ 0*
Is this your first Pucca House?
ANNUAL FAMILY INCOME
Home Loan Amount
Tenure (Years)
Carpet Area in (Sq M)

Subsidy Amount

₹ 0

Subsidy Category

MONTH OF DISBURSEMENT
EXISTING SANCTION AMOUNT
REMAINING TENURE (MONTHS)
EXISTING INTEREST RATE
ABHFL INTEREST RATE (%)

New Eligible Loan Amount

₹ 0

Total Interest

₹ 0

Total Payable Amout

₹ 0

Monthly SIP Amount

₹ 0

Top Up Amount Eligible

₹ 0

Customer Satisfaction Stories

Hear What The Experts Have To Say
Mr. Mohammad Moosa Azmi

Aditya Birla Housing Finance Customer

1 Jan 1
Hear What The Experts Have To Say

Seamless onboarding experience and great support provided by the Relationship Manager during the documentation process.

Hear What The Experts Have To Say
Mr. B. Narsimulu

Aditya Birla Housing Finance Customer

img Hyderabad, India

Hear What The Experts Have To Say
Mr. Kiran Narhari Deshmukh

Aditya Birla Housing Finance Customer

1 Jan 1
Hear What The Experts Have To Say

I appreciate the online documentation process which helped in ease of my loan process. I could get loan information through WhatsApp and other digital platforms.

Hear What The Experts Have To Say
Mr. Vikram Balu Gavali

Aditya Birla Housing Finance Customer

img Belapur, India

Different financial needs, different loans,

Looking for a home loan? Apply online with the ABCD app and get a quick loan. Move into your dream home with a hassle-free loan process.

  • Life Insurance
    Seamless digital application
  • Life Insurance
    Check your EMIs to assess the affordability
  • Life Insurance
    Different loan options for different needs
home loan app QR code

Scan the QR code to download our Mobile App

image_1

FAQs On Housing Finance

ABHFL home loans offer several advantages over other lenders, including:


• Convenient and accessible application process: ABHFL offers an easy online application process, quick approvals, and instant eligibility checks. This makes it easy for borrowers to get the financing they need quickly and efficiently.

• Personalised service: ABHFL provides doorstep services with simplified documentation. This makes the loan process more convenient and hassle-free for borrowers.

• Flexible repayment options: ABHFL offers borrowers a choice between simple EMIs or structured repayments. This allows borrowers to choose the repayment option that best suits their needs and budget.

• Competitive interest rates: ABHFL offers competitive interest rates on its home loans. This can help borrowers save money on their monthly loan payments and over the life of the loan.

• Attractive balance transfer options: ABHFL offers an attractive balance transfer option. This allows borrowers to transfer their existing home loan to ABHFL without any hassle.

• Nil prepayment charges: ABHFL does not charge prepayment penalties on its floating-rate home loans. This gives borrowers the flexibility to repay their loan early without incurring any additional charges.


In addition to these advantages, ABHFL is a reputable and trusted financial institution with a long track record of providing high-quality financial services to its customers.


To apply for an ABHFL home loan, you can follow these steps:


Step 1: Visit the ABHFL website and download the home loan application form.
Step 2: Fill in the application form completely and accurately.

Step 3: Attach the required documents, such as your KYC documents, income proof, property documents, and NOC from your existing lender (if applicable).

Step 4: Submit the duly filled-out form and required documents to your nearest ABHFL branch.

Step 5: An ABHFL representative will review your application and contact you to discuss your loan requirements.

Step 6: Once your loan is approved, you will need to sign the loan agreement and complete the necessary paperwork.


You can also apply for an ABHFL home loan online or by calling the ABHFL customer care number (1800 270 7000). For any assistance, you can also write to us at care.housingfinance@adityabirlacapital.com


Yes, you can jointly apply for a home loan with your spouse or close family members. In such cases, both of your incomes will be considered when calculating the loan amount. However, you will need to provide proof of income for each applicant, such as salary slips, bank statements, and tax returns.


The lender will also consider other factors, such as your credit scores, debt-to-income ratio, and employment history when determining the loan amount and interest rate.


Here are some tips for jointly applying for a home loan:


• Choose a co-applicant with a good credit score. This will help you qualify for a lower interest rate and a higher loan amount.

• Make sure your incomes are stable. The lender will want to see that you and your co-applicant have a stable income to cover the monthly loan payments.

• Have a down payment saved. A down payment will improve your chances of getting approved for a loan and will reduce the amount of money you need to borrow.


Yes, the ABHFL Reference Rate (ARR) can change. It is a benchmark, long-term reference rate that is determined by market conditions and the cost of funds for the company. This means that it can change depending on various external factors, such as economic conditions and interest rates. Additionally, ABHFL may review and revise the ARR from time to time based on its business-specific needs.


ABHFL typically announces any changes to the ARR on its website and through other communication channels. Borrowers are advised to check the ABHFL website regularly for updates on the ARR.


Here are some examples of factors that can affect the ARR:


• Monetary policy: The ARR can be affected by changes in the monetary policy of the central bank. For example, if the central bank raises interest rates, the ARR is likely to increase as well.

• Inflation: Inflation can also affect the ARR. If inflation is high, the lender may increase the ARR to compensate for the rising cost of living.

• Liquidity: The liquidity of the financial system can also affect the ARR. If liquidity is low, lenders may have to pay higher interest rates to attract borrowers.


It is important to note that the ARR is just one of the factors that ABHFL considers when setting interest rates for home loans. Other factors, such as the borrower's credit score, loan amount, and loan term, are also taken into account.


ABHFL reviews its interest rates from time to time and decides whether or not to change them based on market conditions and the cost of funds for the company.


This means that interest rates can change at any time, but ABHFL is committed to providing its customers with competitive interest rates and terms. Borrowers are advised to check the ABHFL website regularly for updates on interest rates.


The PNI sanction letter is valid for 90 days from the date of issue. However, if the loan is not drawn within 30 days of the issue date, a fresh sanction letter will need to be obtained. This is because the lender may need to reassess the borrower's creditworthiness and the market value of the property before disbursing the loan. Additionally, the terms and conditions of the loan offer may change over time, so it is important to obtain a fresh sanction letter if the loan is not drawn within the specified timeframe. To avoid any delays or inconvenience, it is recommended that borrowers draw their loan within 30 days of the issue date of the PNI sanction letter. If you have any questions or concerns, please do not hesitate to contact us.

An equated monthly instalment (EMI) is a fixed payment amount that borrowers make to lenders on a specified date each month. EMIs are applied to both interest and principal each month so that, over a specified period of time, the loan is paid off in full.


EMI repayment typically commences from the month following the month in which the full loan amount is disbursed. However, some lenders may offer a grace period before EMI repayment begins.


EMIs are a convenient way for borrowers to repay their loans, as they allow borrowers to budget for their monthly loan payments in advance. Additionally, EMIs can help borrowers stay on track with their loan repayments and avoid defaulting on their loans.


Here is an example of how an EMI is calculated:


EMI = (Loan Amount X Monthly Interest Rate X (1 + Monthly Interest Rate)^Loan Tenure in Months) / ((1 + Interest Rate)^Loan Tenure in Months - 1)


For example, if a borrower takes out a loan of ₹ 25 lakhs at an interest rate of 8% per annum for a period of 10 years, their monthly EMI would be ₹ 30,347.


Loan amount: ₹ 25 lakhs

Interest rate: 8% per annum

Loan term: 10 years


Step 1: Convert the interest rate to a monthly rate.


Monthly interest rate = Annual interest rate / 12 / 100

Monthly interest rate = 8 / 12 / 100 = 0.00667


Step 2: Calculate the exponential factor.


Exponential factor = (1 + Monthly interest rate)^Loan tenure in months

Exponential factor = (1 + 0.00667)^120 = 2.21964


Step 3: Calculate the EMI.


EMI = (Loan amount * Monthly interest rate * Exponential factor) / (Exponential factor - 1)


EMI = (2500000 * 0.00667 * 2.21964) / (2.21964 - 1)


EMI = 30,347


Therefore, the monthly EMI for the loan is ₹ 30,347.


Pre-EMI interest is the interest charged on the disbursed portion of the loan amount until the start of the EMI repayment schedule. It is calculated on a monthly basis and is typically payable from the date of each disbursement.


Pre-EMI interest is charged because the borrower can use the disbursed portion of the loan amount even before the EMI repayment schedule begins. This gives the borrower a head start on their projects, such as home construction or renovation, and allows them to generate income from the property (if applicable) before they have to start making full EMI payments.


The amount of pre-EMI interest charged will vary depending on the loan amount, interest rate, and disbursement schedule. Borrowers should carefully review their loan agreement to understand the pre-EMI interest charges that will apply to their loan.


All unbanked/unused cheques in the custody of ABFL or ABHFL, such as post-dated cheques, undated cheques, and security post-dated cheques, will be cancelled and destroyed without any intimation to the customer after the closure of the loan account.


This is done to protect the customer from fraud and to ensure that the cheques cannot be used once the loan account is closed.


Yes, ABHFL offers home loans for a variety of purposes, including:


• Home purchase

• Home construction

• Home repairs and improvements

• Home extension

• Plot purchase and home construction


ABHFL understands that your home is your most important asset, and it is committed to providing you with the financing you need to make your homeownership dreams a reality. Whether you are looking to purchase a new home, build your dream home, or renovate your existing home, ABHFL can help.


To learn more about ABHFL home loans for home improvements or home extensions, please visit the ABHFL website or contact an ABHFL representative.


ABHFL complies with a variety of rules and regulations, including:


• The Companies Act, 2013

• The Securities and Exchange Board of India (SEBI) (Listing Obligations and Disclosure Requirements) Regulations, 2015

• The National Housing Bank (NHB) Housing Finance Companies (Regulation and Supervision) Act, 1992

• The Reserve Bank of India (RBI) Guidelines on Fair Practices Code for Non-Banking Financial Companies (NBFCs)

• The RBI Guidelines on Prudential Framework for Housing Finance Companies (HFCs)

• The RBI Guidelines on Know Your Customer (KYC) and Anti-Money Laundering (AML)


ABHFL also has its own corporate governance code, which is aligned with the best practices recommended by the Securities and Exchange Board of India (SEBI) and the National Housing Bank (NHB).


The ABHFL corporate governance code includes provisions for the following:


• The composition and role of the board of directors

• The role of the audit committee, nomination committee, and risk management committee

• The company's policies on conflict of interest, insider trading, and corporate social responsibility


ABHFL is committed to following all applicable rules and regulations and to maintaining the highest standards of corporate governance. This commitment is essential to building trust with its customers and stakeholders and to ensuring the long-term success of the company.


In addition to the above, ABHFL also complies with all other relevant laws and regulations, such as the Real Estate (Regulation and Development) Act, 2016, and the Insolvency and Bankruptcy Code, 2016.